

ComplianceOne Insurance Newsletter –
September 2026

The topics discussed in this monthly newsletter are as follows:
Enforcement News
Regulatory Updates
IA Publishes Conduct in Focus Issue 13 on Marketing, Self-Referral and Responsible Officer Standards
Market News
Enforcement News
1. IA Orders FWD Life (富衛人壽) to Pay HK$19.5 Million for Shortcomings in Anti-Money Laundering Controls
On 24 September 2026, the Insurance Authority (“IA”) ordered FWD Life Insurance Company (Bermuda) Limited (“FWD Life”) (富衛人壽) to pay a pecuniary penalty of HK$19.5 million. The action follows an on-site inspection under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance (Cap. 615) (“AMLO”) and was taken under section 21(2) of AMLO.
The IA found that, during periods between April 2012 and September 2024, FWD Life contravened various AMLO requirements. The shortcomings were in payor identification on third-party payments, controls on potentially suspicious transactions including cash payments, data capture and screening of politically exposed persons (“PEPs”), and customer due diligence on particular transactions.
The material findings in the Statement of Disciplinary Action are set out below:
Period | Material Findings |
April 2012 – November 2020 | Data gaps meant beneficial owners of trust and legal-entity policy holders were not screened for PEP status, at onboarding or on an ongoing basis. |
April 2012 – September 2024 | FWD Life failed to identify 58 customers or beneficial owners as PEPs, including 7 foreign or non-Hong Kong PEPs, and did not carry out enhanced due diligence or obtain senior management approval. |
January 2021 – December 2023 | Of 129 bank drafts sampled (HK$400,000 to HK$4.7 million), 3 had no Premium Payment Declaration or other proof. Of the remaining 126, the draft was not purchased by the policy holder, insured or settlor in 68 cases. |
January 2022 – December 2022 | No follow-up procedures on unexplained split cash premiums. 306 policies with split cash payments were not examined. |
24 September 2026 | Pecuniary penalty of HK$19.5 million. |
FWD Life’s own payment-acceptance procedures required a copy of the bank-draft application so the payor could be identified. In practice those procedures did not come into effect, or had been superseded. FWD Life has since implemented remedial measures. The IA acknowledged the early acceptance of the findings. After enhanced reviews, FWD Life confirmed there had been no onboarding of non-eligible customers as a result of delayed detection.
SIGNIFICANCE:
Every authorized insurer carrying on long term business must keep effective anti-money laundering and counter-terrorist financing controls. A written procedure that the business does not actually use is the failure the IA priced at HK$19.5 million. For intermediaries, the exposure is in how premiums are collected: a Premium Payment Declaration that does not match the true payor, and unexplained split cash that is booked rather than escalated, are the samples the inspection used.
2. IA Prohibits Seven Insurance Intermediaries for up to 42 Months for Misappropriating Client Premiums Totalling HK$714,870
The IA has prohibited seven insurance intermediaries from acting as insurance intermediaries for up to 42 months, after finding that they misappropriated client premium payments totalling HK$714,870.
What the IA Found
Some of the methods of misappropriation include the agent having falsely represented to the client that the premium was used to purchase a policy when the agent had misappropriated it. To conceal the agent’s conduct, she bought a policy a year later by using the client premium payments to renew the original policy. In another case, the agent ceased to be the client’s servicing agent, but he continued to assist the client with his policies and misappropriated the premium payments, causing them to lapse. Unaware the policies had lapsed, the client continued to pay further premium payments to the agent, who misappropriated it.
See below table for more details:
Name | License No. | Type | Date of Action | Sanction |
Mr. CHOW Ping Kei (周炳基)
| IG3047 | Individual Insurance Agent | 16 June 2026
| Prohibition for 42 months, commencing 16 June 2026 |
Mr. JIN Wen (金文) | IJ6047 | Individual Insurance Agent | 14 April 2026
| Prohibition for 29 months, commencing 14 January 2026
|
Mr. LO Chin Pang Tony (盧展鵬) | IA6496 |
| 15 May 2026
| Prohibition for 12 months, commencing 15 February 2026
|
Ms. PANG Hok Yee (彭學而) | IJ4802 | Individual Insurance Agent | 1 May 2026
| Prohibition for 10 months, commencing 1 December 2025
|
Ms. SO Men Yu (蘇玟瑀) | IF6317 | Individual Insurance Agent | 3 June 2026
| Prohibition for 30 months, commencing 3 March 2025
|
Ms. YAU Po Lai (邱寳麗) | IF9730 | Individual Insurance Agent | 18 May 2026
| Revocation of licence and prohibition for 20 months, commencing 18 May 2026
|
Ms. ZHOU Min (周敏) | IG2955 | Individual Insurance Agent | 24 April 2026
| Prohibition for 9 months, commencing 24 April 2026
|
Source: Register of Licensed Insurance Intermediaries
SIGNIFICANCE:
The IA said the conduct seriously impugned the individuals’ fitness and properness and severely affected policyholders. It reminded the public to review their portfolios regularly and to pay premiums only through channels designated by the insurer.
Regulatory Updates
3. IA Publishes Conduct in Focus Issue 13 on Marketing, Self-Referral and Responsible Officer Standards
On 30 September 2026, the IA published Conduct in Focus Issue 13, by circular to chief executives of authorized insurers and responsible officers of licensed insurance agencies and broker companies. The edition covers complaint statistics for the first half of 2026, responsible marketing, a social-media rumour about the professional-investor exemption, the Key Person in Control Function for Intermediary Management, self-referral arrangements, responsible-officer fit and proper assessments, insurance fraud, and recent enforcement on agent-manager accountability.
***English version: Conduct in Focus - September 2026
***中文版: 監管通訊- 2026年9月
Significant Topics and Shares
1) Responsible officers, tenure is now a conduct signal.
Between 23 September 2019 and 30 June 2026, the IA approved 3,201 individuals as responsible officers of licensed insurance agencies and broker companies. The edition treats short tenure, particularly at broker companies writing long-term business on a referral model, as a conduct-risk signal. Candidates from that segment are more likely to be interviewed before approval, and a pattern of short tenures can lead to a supervisory review or an on-site inspection.
Measure | Figure |
RO approvals, 23 Sep 2019 – 30 Jun 2026 | 3,201 individuals |
Average active tenure, all entities | 3.8 years |
Average tenure, broker companies / agencies | 2.3 years / 3.3 years |
Long-term business entities, appointments under 2 years | 51.4% |
All lines, tenures of 3 years or more | 53.4% |
ROs with a single appointment record | 81.4%, averaging 3.5 years |
The IA restates the role of the Key Person in Control Function for Intermediary Management. Oversight of intermediaries is treated as a control function that has to be staffed and used, not a title on the return.
2) Agent-manager accountability
Two recent cases are used to show that a manager who facilitates misconduct, rather than stopping it, is within the IA’s reach. For both cases, the IA found grounds to question fitness and properness.
In February 2026 the IA banned a former agent after she directed a downline to give the regulator a misleading response, following the discovery that the downline had submitted a false academic certificate to an insurer.
In May 2026 an agent manager provided her login credentials to an unregistered downline, who then completed a Mandatory Provident Fund consolidation application that the client later said was not authorised.
3) Complaint statistics (1 January to 30 June 2026)
| The IA received 652 complaints in the first half of 2026, a 10% increase on the same period in 2025. The IA describes the number as still modest against the growth in premiums. The largest category, Business or Operations, rose 9% year on year, driven by failures to assign a servicing agent after intermediary turnover.
|
4) Fake news, and the professional-investor exemption | The edition uses a social-media rumour as a teaching case. Posts claimed that law enforcement had made multiple arrests at unnamed insurance firms for deliberately falsifying information so that customers would be classified as professional investors, in order to avoid the commission-spreading requirements.
The IA says that account was wrong: there were no such arrests. The learning point is the one the rumour got right in substance. Classifying a customer who is not a professional investor as one, so that commission can be front-loaded in year one, would be a misuse of the exemption in the Practice Note on remuneration structures for participating policies.
|
5) Self-referral does not pass the duck test | The IA describes an emerging arrangement it calls “self-referral”: a customer, or a family member, enters a referral agreement with a broker so that a fee is routed back as an effective rebate. The IA’s position is that the label does not matter. If it looks like undocumented rebating, it is undocumented rebating, and it is prohibited. In the past few months the IA imposed licence-renewal conditions on three broker companies for failing to control referral activities, including a prohibition on accepting any new referral business.
The edition places this against the existing framework: the 22 May 2024 circular on controls for life-insurance referral business, the 1 September 2025 circular on an acceptable benchmark for referral fees on participating policies, and the commission-spreading Practice Note, in force from 1 January 2026, under which no more than 70% of total commission is paid in the first policy year. Unlicensed referrers may introduce a customer. They may not advise, explain the product, or sell.
|
6) Responsible marketing | Gaps between promotion and protection as clickbait becomes a normal digital sales tool. The IA treats selective statistics in digital advertising.
A campaign that repeatedly produces misunderstandings is to be amended or withdrawn.
|
SIGNIFICANCE:
Issue 13 does not create a new rule. It shows how the IA is applying rules already in force. Four points should be on the compliance file this month. A fee paid back to a customer, or to a family member, under a referral agreement is undocumented rebating and is prohibited; three broker companies have already had licence-renewal conditions imposed for weak referral controls, including a bar on new referral business. Short responsible-officer tenure, particularly at a broker company writing long-term business on a referral model, is a supervisory signal and may lead to an interview, a review, or an on-site inspection. A digital campaign built on selective statistics that repeatedly misleads customers is expected to be amended or withdrawn. Classifying a customer who is not a professional investor as one, in order to front-load commission, sits outside the Practice Note.
Insurers and appointing principals should treat referral controls, responsible-officer continuity and marketing governance as one conduct risk, and should confirm that the Key Person in Control Function for Intermediary Management is exercising oversight, not holding a nominal appointment.
Markets News
4. IA Hosts Belt and Road Panel on Hong Kong as a One-Stop Risk Advisor for Mainland Enterprises Going Global
On 9 September 2026, the IA hosted a panel at the Belt and Road Summit, themed “Architecting a Global Risk Strategy: Hong Kong as the End-to-End Risk Advisor for Globalizing Enterprises”.
The session brought corporate executives and risk experts together to discuss the risk spectrum facing Chinese Mainland enterprises expanding overseas, the tools available to manage those risks, and how Hong Kong can act as a one-stop risk advisor.

Source: IA Press Release
Mr. Clement LAU (“LAU”), Executive Director, Policy and Legislation of the IA, and moderator of the panel, said the Belt and Road Initiative has moved from standalone infrastructure projects to the operation of global business ecosystems, and that enterprises need proactive and consolidated risk management to deal with that complexity. LAU said Hong Kong’s depth in insurance solutions and professional advisory services puts it in a position to support Mainland enterprises from risk assessment through to tailored mitigation.
SIGNIFICANCE:
The panel set out Hong Kong’s risk-management toolkit, and how those solutions can be scaled for large enterprises and for small and medium-sized enterprises. Panellists also looked at the city’s advisory cluster, maritime law, trade finance and insurance, as the basis of a seamless one-stop offering, and at what Hong Kong still needs if it is to remain the preferred risk advisor for Mainland enterprises going global.
5. IA Chairman and Chief Executive Officer Meet the National Financial Regulatory Administration
On 10 September 2026, the IA announced that Mr. Stephen YIU (“YIU”), Chairman of the IA, and Mr. Clement CHEUNG (“CHEUNG”), Chief Executive Officer of the IA, visited the National Financial Regulatory Administration (“NFRA”) (國家金融監督管理總局) in Beijing the previous week. They met Mr. XIAO Yuanqi (“XIAO”), a member of the NFRA CPC committee and Vice Minister of the NFRA, on the afternoon of 3 September 2026.

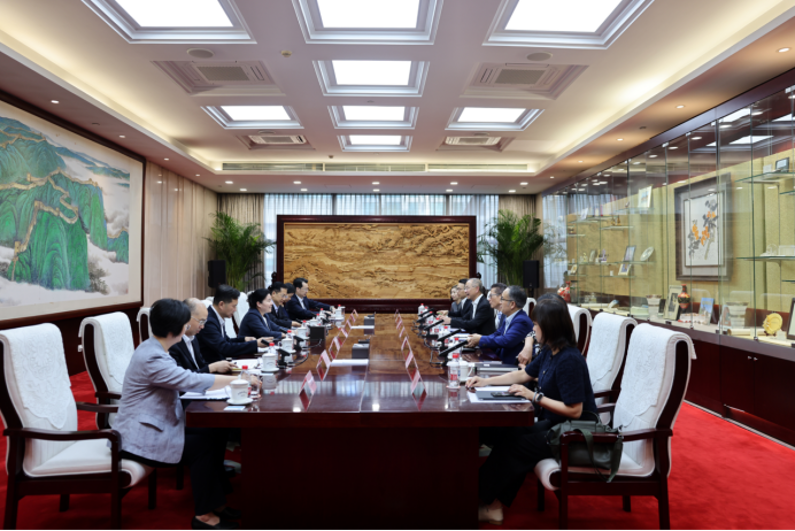
Source: IA Press Release; NFRA Press Release 2026-09-22
The two sides exchanged views on how Hong Kong’s insurance industry can be further integrated into overall national development, and on regulatory priorities and collaboration.
SIGNIFICANCE:
The meeting is short on public detail, but it sits next to the Belt and Road panel of the day before. Cross-boundary insurance, captive and specialty capacity, and supervisory cooperation with the NFRA are the channels through which the “risk management hub” line becomes operating business. Intermediaries with Mainland-visitor or outbound-enterprise books should expect that cooperation to show up later in product, referral and conduct expectations, not only in communiqués.
[End of ComplianceOne Insurance Newsletter – September 2026]
For more details, please click on the title of the topic above.
=================================
~ Make It Right Today, Better Tomorrow ~
=================================
The Newsletter is for general information purpose only and is not intended to constitute legal or other professional advice.
For enquiries, please email to support@complianceone.hk or WhatsApp us at (852) 95164607.
Unit 1605, 16/F, West Tower, Shun Tak Centre,168-200 Connaught Road Central,
Sheung Wan, Hong Kong
Tel: (852) 3955 0277 www.complianceone.hk